Debt Relief Offers? The Catch
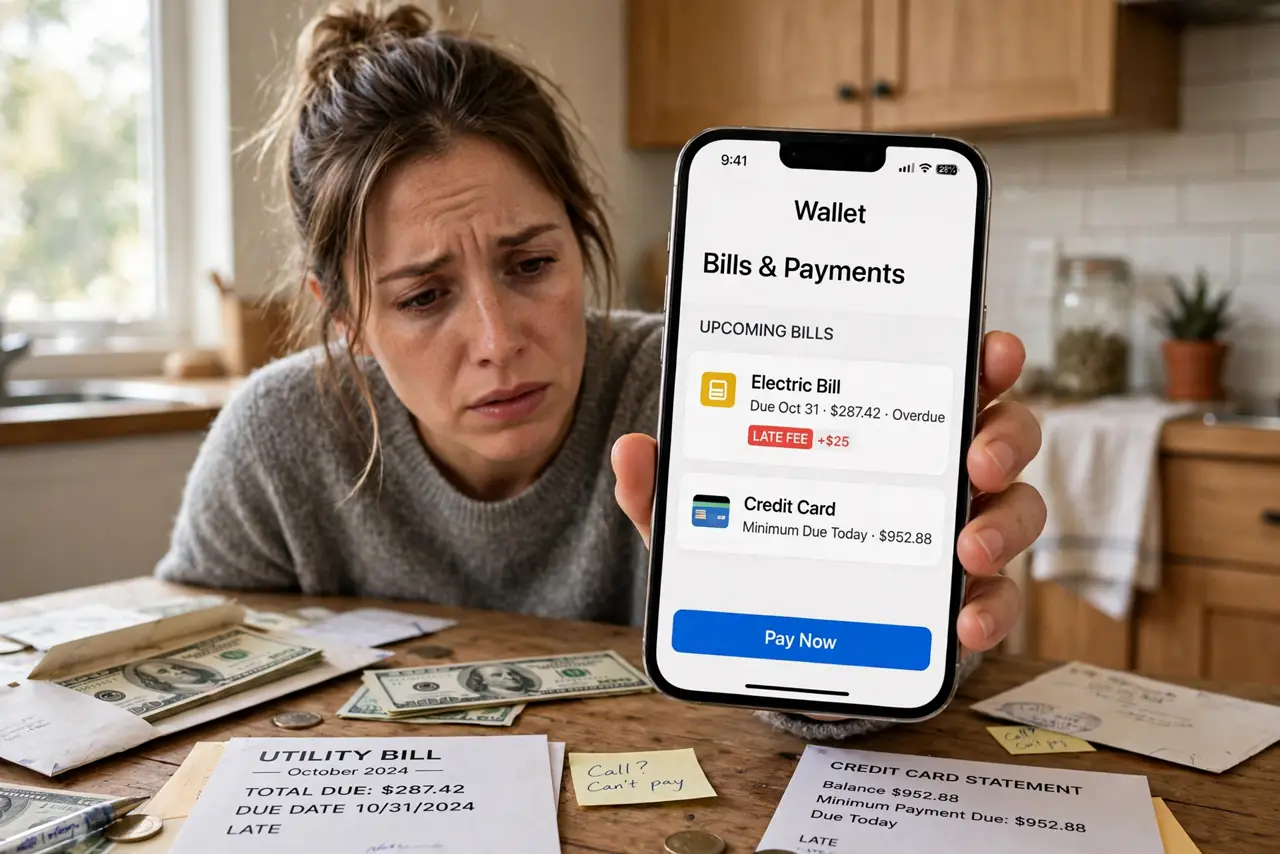
Drowning in debt makes any lifeline tempting — and scammers know it. 'Cut your debt in half, guaranteed!' The catch: upfront fees, wrecked credit, and 'programs' that are just you not paying bills while they collect. Real debt help exists, but it never looks like a robocall promise.
TL;DR / Quick Fix
Quick fix: never pay upfront fees for debt relief — legitimate counselors charge little or nothing until services are delivered. Check any company with your state attorney general and the FTC before signing. For free, trustworthy help, contact a nonprofit credit counseling agency instead.
Follow these steps
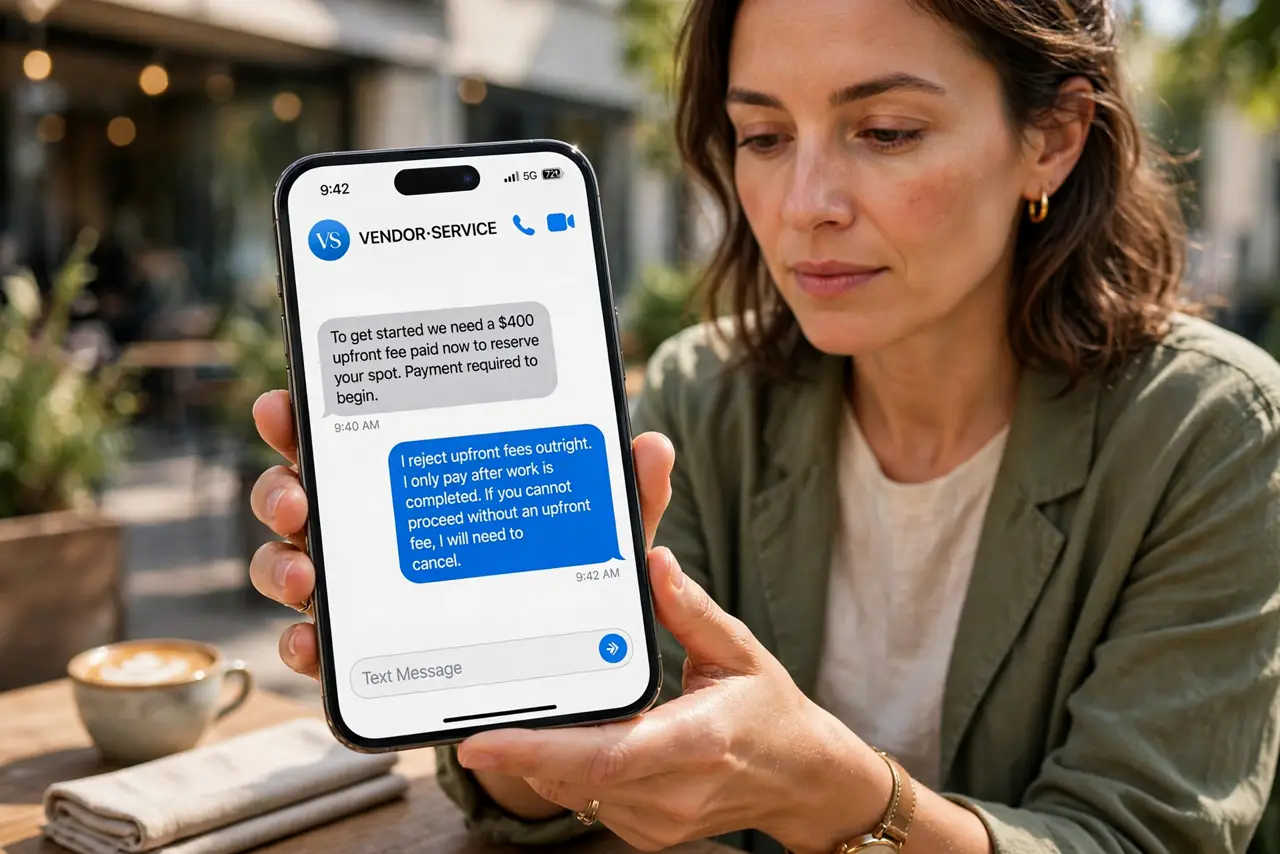
- Reject upfront fees outright. Charging before delivering debt-relief services is illegal for many such companies — and it is the scammer's whole revenue model. Fee-first equals walk away.
- Distrust guarantees. 'Cut your debt half, guaranteed!' Nobody can guarantee creditor behavior. Guarantees in debt relief are marketing, not contracts.
- Understand the 'stop paying' trap. Many schemes tell you to stop paying bills while they 'negotiate.' Your credit craters, late fees pile up, and the 'negotiation' never happens.
- Vet every company. Check the state attorney general, the FTC, and the Better Business Bureau for complaints and actions. Ten minutes of searching reveals most bad actors.
- Use nonprofit counseling instead. Nonprofit credit counseling agencies offer free or cheap guidance, real budgets, and legitimate debt-management plans — the boring, effective alternative.
- Talk to your creditors directly. Hardship programs, reduced rates, and payment plans often come straight from the creditor — no middleman, no fee. One awkward call beats one expensive scam.
What NOT to do
- Do not sign over power of attorney to a relief company. That document lets them act as you — with your creditors and your money.
- Do not stop paying bills on a stranger's advice. The credit damage is yours; the fee savings are theirs.
- Do not trust testimonials on their site. Reviews are bought; enforcement actions are public — check the latter.
- Do not confuse 'debt settlement' ads with 'debt management.' Settlement tanks credit and invites lawsuits; counseling preserves options.
Frequently asked questions
Is debt settlement ever legitimate?
Sometimes, through attorneys or careful negotiation — but it damages credit and can trigger tax bills on forgiven amounts. It is a last resort, not a robocall special.
What does nonprofit credit counseling cost?
Usually free for the counseling session; debt-management plans carry small monthly fees. Compare that to the thousands fee-first companies demand upfront.
Can a company really make debt 'disappear'?
No. Debts are settled, paid, discharged in bankruptcy, or expire — never vanished by a phone pitch. Anyone promising disappearance is selling fiction.
What to read next
- Credit Repair Promises? The Truth
- Freeze Your Credit? How To