Freeze Your Credit
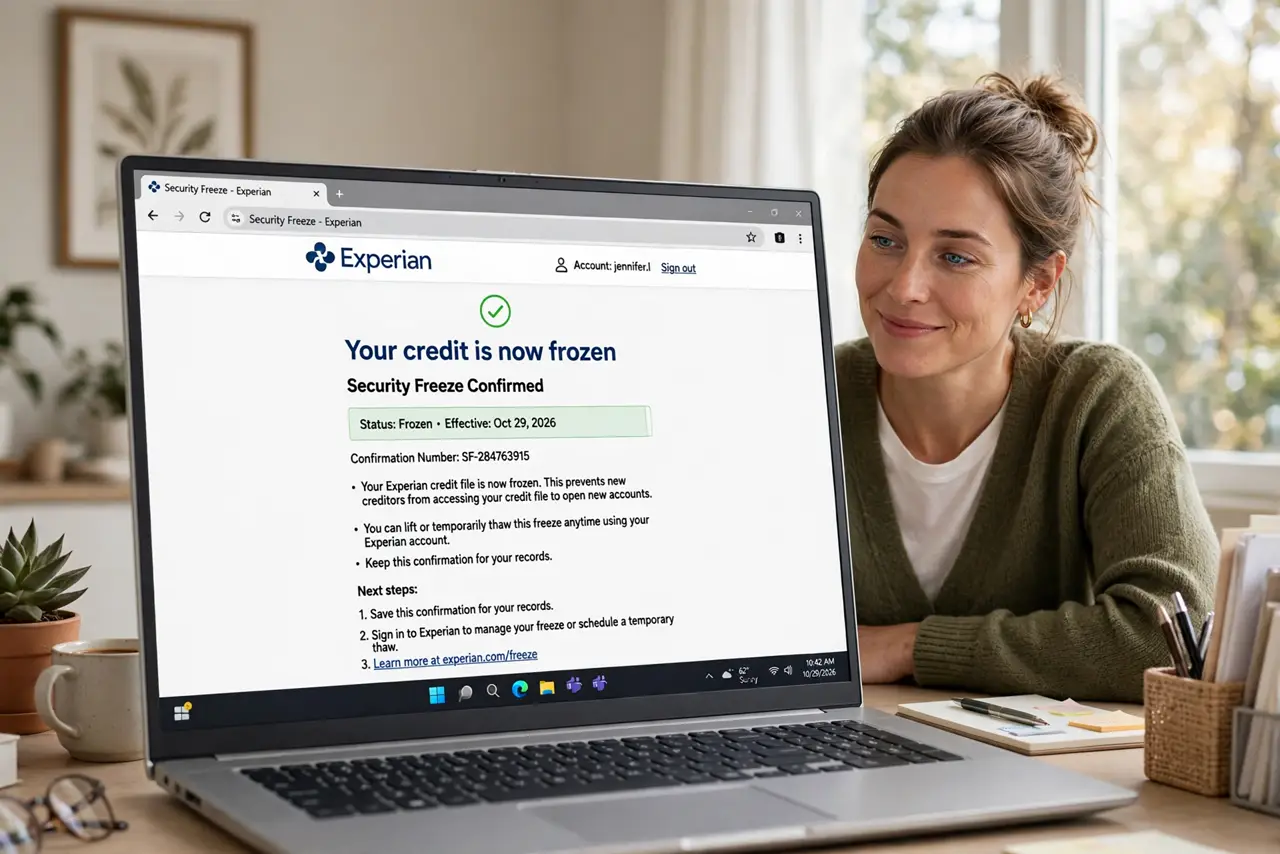
Your data has leaked in a breach — again — and now anyone can apply for credit in your name. A credit freeze locks your credit files so no new accounts open without you thawing them first. It is free, it is the strongest protection against new-account fraud, and it takes about twenty minutes across the three bureaus.
TL;DR / Quick Fix
Quick fix: contact each of the three major credit bureaus online or by phone and place a security freeze — it is free by law. Keep each bureau's PIN or login safe. Thaw temporarily when you apply for credit yourself; refreeze after. Do this before you need it.
Follow these steps
- Understand what a freeze does. A freeze blocks access to your credit file, so lenders cannot pull it — and without the pull, new accounts cannot open. Your existing cards and loans work normally; only new applications stop.
- Freeze at all three bureaus. Place the freeze with Equifax, Experian, and TransUnion separately — each holds its own file. One bureau frozen while two stay open is a two-thirds solution.
- Save each PIN or login. Each bureau gives you credentials to manage the freeze. Store them with your important documents — losing them turns a future thaw into a bureaucratic quest.
- Thaw when you apply. Applying for a card, loan, or apartment? Thaw the relevant bureau temporarily — a one-day or one-week lift — then let it refreeze. Ask the lender which bureau they pull.
- Know it is free. Freezes and thaws are free by federal law — anyone charging you is a scam or a paid lookalike service. Use each bureau's official site directly.
- Pair with a fraud alert. A freeze stops new accounts; a fraud alert adds a verification step for extra caution. Together they are the complete identity-theft defense for credit.
What NOT to do
- Do not pay for a freeze. Freezes are free by law — paid 'credit lock' products sell you what the freeze gives away.
- Do not freeze only one bureau. Lenders pull different bureaus; all three must be frozen for real protection.
- Do not lose the PINs. A freeze you cannot lift is its own problem — store credentials where you store passports.
- Do not confuse freeze with monitoring. Monitoring tells you after fraud happens; a freeze prevents it — do the freeze first.
Frequently asked questions
Will a freeze hurt my credit score?
No. Freezing has zero effect on your score — it only controls who can see the file, not what is in it.
How fast does a thaw work?
Online thaws are usually instant to an hour. Phone and mail take longer — plan ahead before applying for credit.
Should I freeze my child's credit too?
Yes — child identity theft is real and often undiscovered for years. Bureaus let parents freeze minors' files.