Freeze Credit at Each Bureau
After a data breach or a scare like a SIM swap, everyone says 'freeze your credit' — but then you discover there is not one credit bureau, there are three (in the US), and each needs its own freeze. It sounds like a chore; it takes about fifteen minutes total and it is the strongest free protection against new-account fraud.
TL;DR / Quick Fix
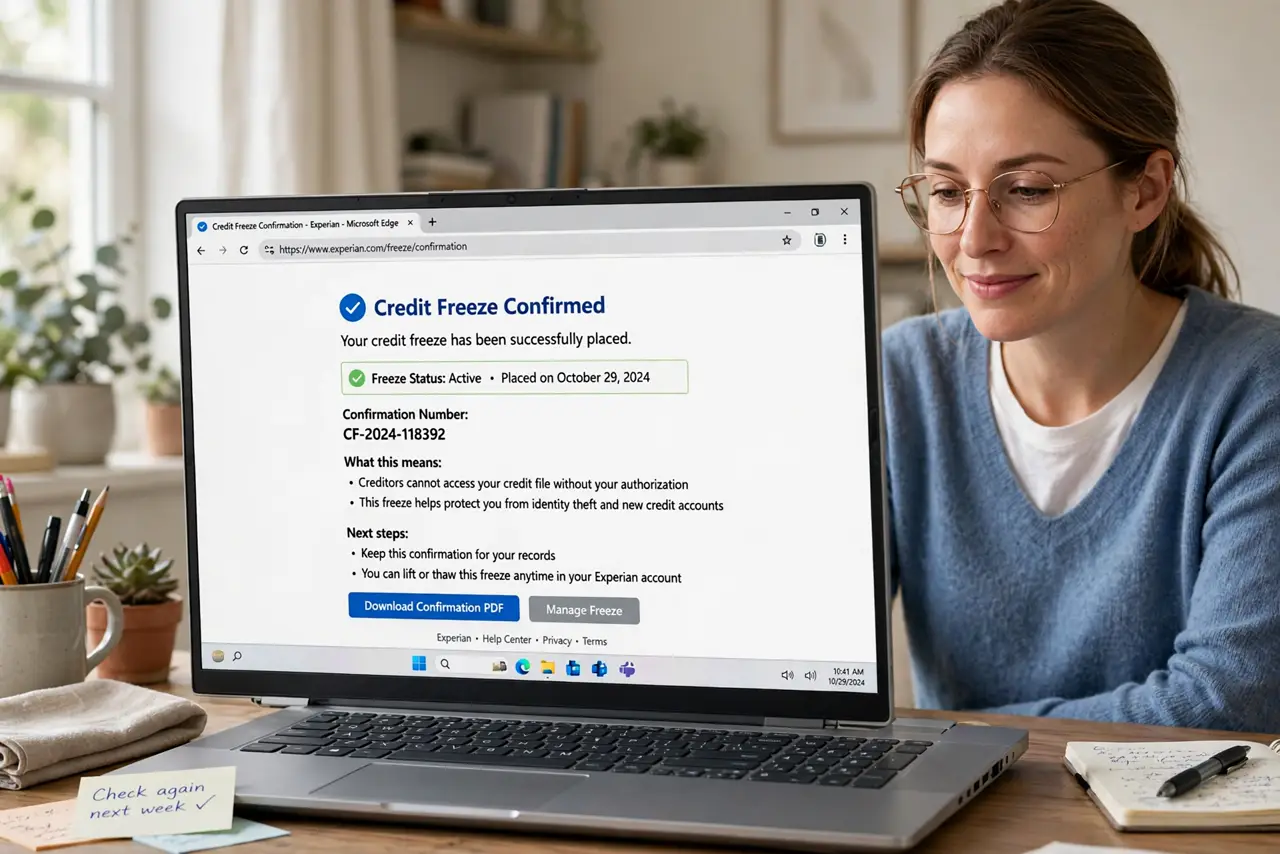
Quick fix: freeze your credit at all three major bureaus — Equifax, Experian, and TransUnion — online or by phone, free. A freeze blocks new accounts opened in your name. You will briefly lift it when you apply for credit yourself.
Follow these steps
- Understand what a freeze does. A freeze locks your credit file so lenders cannot pull it — and no pull means no new account in your name. It does not affect your score or existing accounts.
- Freeze all three bureaus. Equifax, Experian, TransUnion — each separately, online or by phone. Freezing one leaves the other two open; do all three in one sitting.
- Save your PINs. Each bureau gives you a PIN or password to lift the freeze later. Store them in a password manager — losing them turns a future car loan into a hassle.
- Know freeze vs. lock. A freeze is the free, legally-backed option; a 'lock' is often a paid product feature. See freeze vs lock — for most people, the free freeze wins.
- Lift temporarily when you apply. Applying for a card or loan? Ask the lender which bureau they pull, lift just that one for a day, then refreeze. Takes minutes online.
- Freeze children's files too. Kids' clean files are prime targets. All three bureaus let parents freeze a minor's file by mail — worth doing once.
What NOT to do
- Do not freeze just one bureau. Attackers try all three — a single freeze is a two-thirds-open door.
- Do not pay for a 'credit lock' thinking it is required. The freeze is free by law; locks are upsells.
- Do not lose your lift PINs. Store them where you will find them in two years, not on a sticky note.
- Do not assume a freeze stops all fraud. It blocks new accounts, not misuse of existing ones — keep monitoring those.
Frequently asked questions
Does freezing hurt my credit score?
No. A freeze is invisible to scoring — it only blocks new inquiries.
How do I start?
Visit each bureau's freeze page directly — see the step-by-step — or call them; it is free either way.
How fast does a freeze take effect?
Online freezes are usually instant; lifting one can take minutes to an hour. Plan ahead before applying for credit.