Phone Insurance? Basics
Phone insurance promises a cheap replacement when your phone meets concrete, water, or a thief — for a monthly fee plus a deductible per claim. Whether it beats self-insuring depends on your butterfingers coefficient and your phone's price. Here is the honest breakdown of what the plans cover and when they pay.
TL;DR / Quick Fix
Quick fix: phone insurance makes sense for expensive phones owned by drop-prone people — compare the yearly premiums plus deductible against the phone's repair or replacement cost. Carrier plans, AppleCare+, and third-party insurers differ wildly; read the claim limits before paying. Often, a good case plus self-insurance wins.
Follow these steps
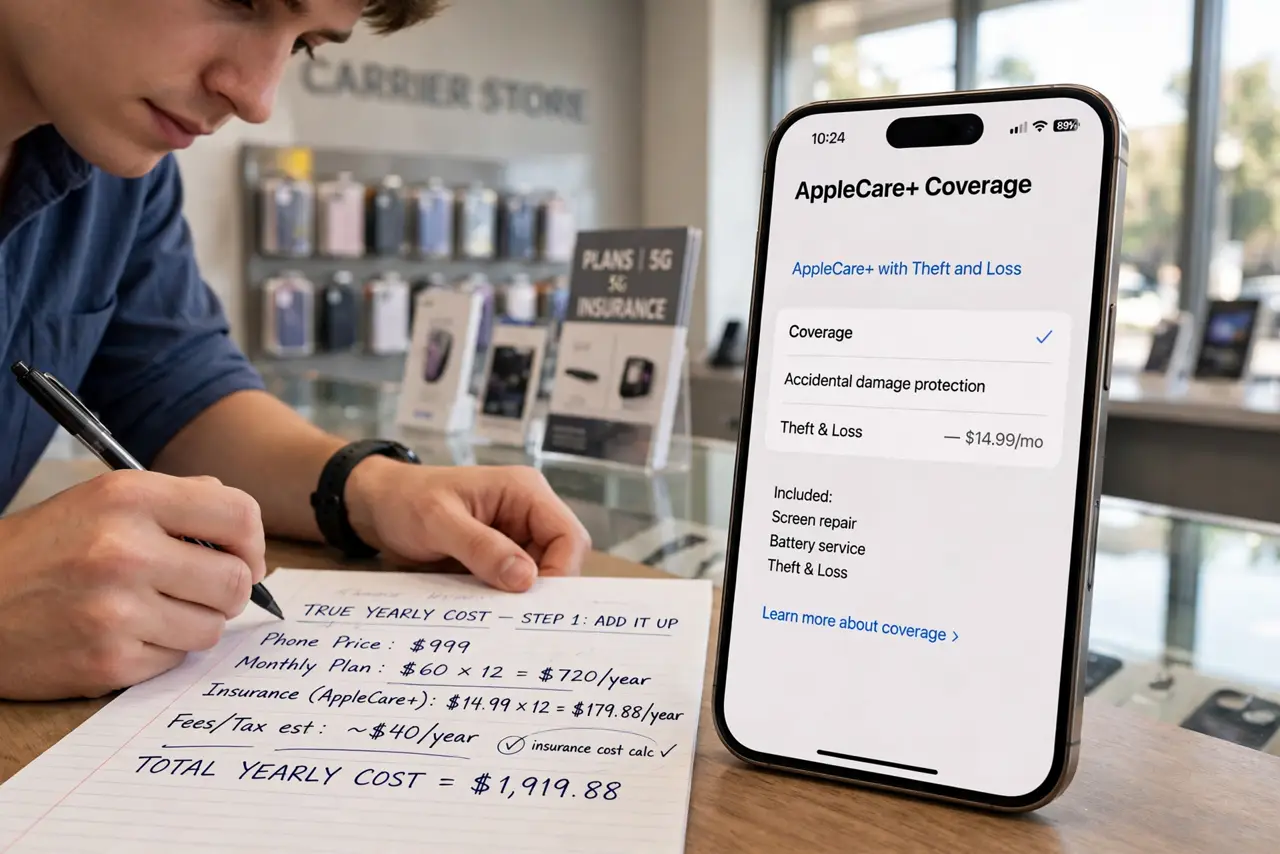
- Add up the true yearly cost. Monthly premium × 12 + deductible per claim = your real price. A $12/month plan with a $200 deductible costs $344 before it helps you once — do that math first.
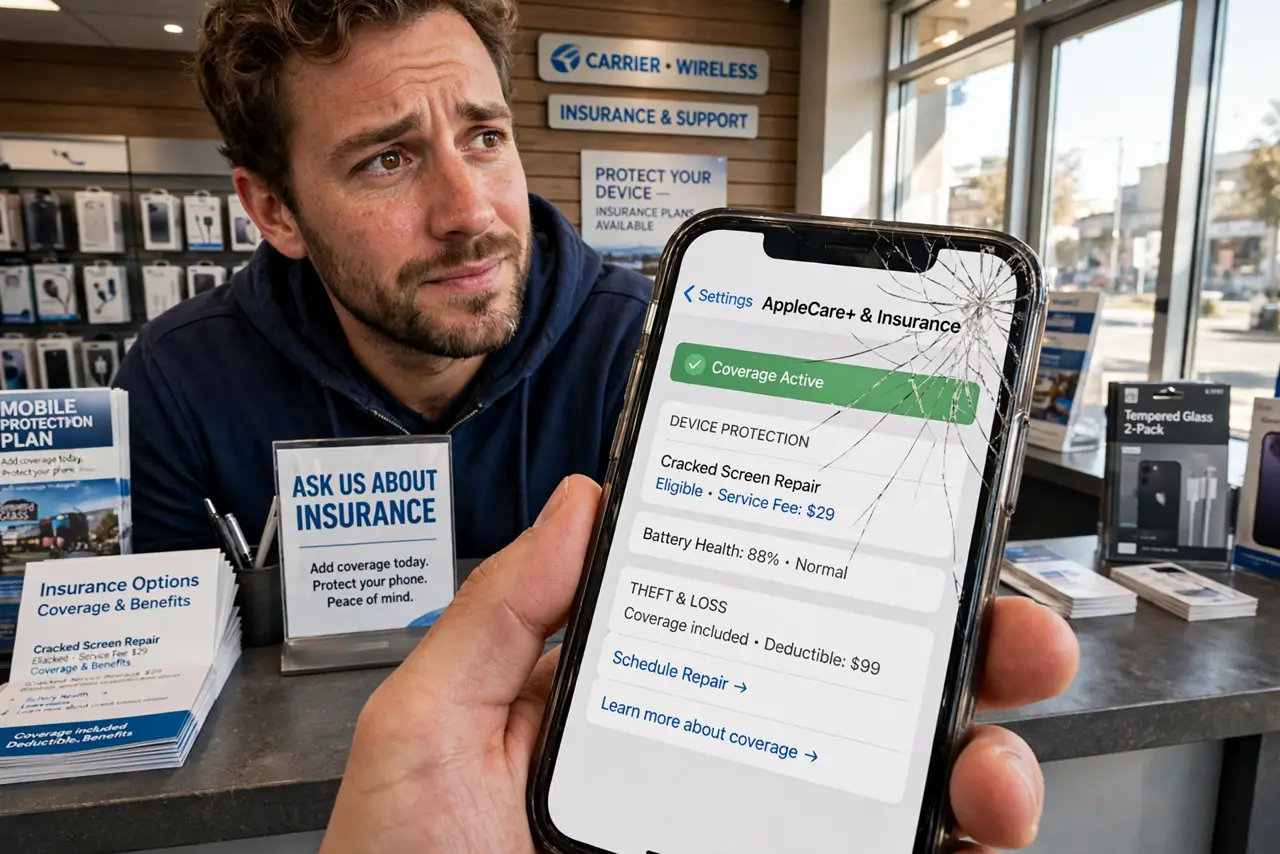
- Check what is actually covered. Accidental damage is standard; theft and loss often cost extra or are excluded entirely. Water damage has fine-print limits — read the covered-perils list, not the brochure.
- Compare the three sources. Carrier plans bundle with your bill; AppleCare+ offers the best repair quality for iPhones; third parties compete on price with slower service. Get quotes from all three.
- Mind the claim limits. Most plans cap claims per year and replace with refurbished units — not new phones. Two incidents in a year can exhaust a plan that looked generous.
- Consider the case alternative. A $50 rugged case plus a screen protector prevents most claims entirely. The cheapest insurance is not breaking the phone — boring but true.
- Know the enrollment window. Like extended warranties, phone insurance usually requires signup within 30-60 days of purchase. Miss it and the option is gone until your next phone.
What NOT to do
- Do not buy insurance after the damage. Plans have waiting periods and inspect for pre-existing damage — fraud flags follow you.
- Do not ignore the deductible math. Premium + deductible near repair cost means you are prepaying, not insuring.
- Do not assume theft is covered. Many base plans exclude it — verify before your phone walks away, not after.
- Do not stack overlapping coverage. AppleCare+ plus carrier insurance on one phone is paying twice for the same cracked screen.
Frequently asked questions
Is phone insurance worth it for a cheap phone?
Rarely — when premiums plus deductible approach the phone's value, self-insure. Insurance math favors expensive flagships.
Carrier insurance vs AppleCare+ — which is better?
AppleCare+ wins on repair quality and speed for iPhones; carrier plans win on theft/loss bundling. Pick by your bigger fear: drops or disappearance.
What voids phone insurance?
Unauthorized repairs, intentional damage, and sometimes rooting/jailbreaking. Read the exclusions — they are enforced at claim time.